Hong Kong Insurers Forge Tech Alliances amid Tax Rules
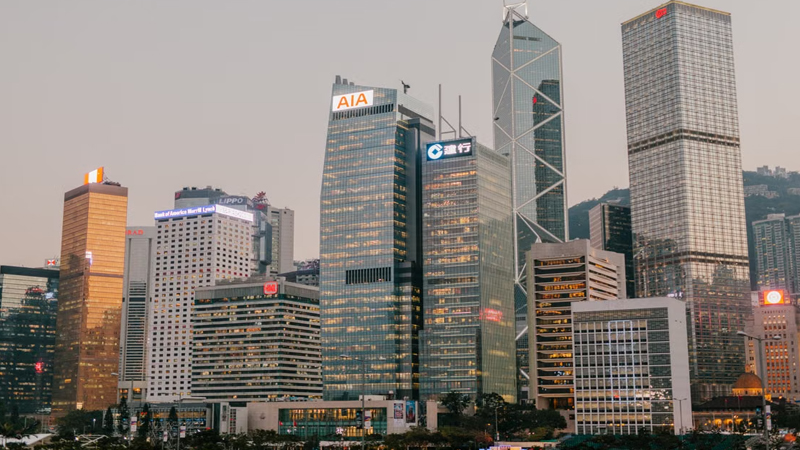
Int’l Insurance Desk: Hong Kong insurers are moving quickly to form new technology partnerships as they navigate tighter tax rules from mainland China that have added pressure on cross-border business. According to a report in the South China Morning Post published on September 9, companies including Prudential, Manulife and BOC Life are striking deals that range from artificial intelligence tools to healthcare services in an effort to improve efficiency and stay competitive.
Prudential announced a collaboration with Alibaba Cloud to introduce an AI underwriter. The system lets financial consultants enter a client’s financial details, medical history, occupation and residential information and receive a preliminary underwriting indication within minutes rather than days.
Lawrence Lam, chief executive of Prudential Hong Kong, told reporters that insurers working alone would struggle to keep up with new technology and that those who use AI most effectively will come out ahead. Alibaba Cloud executives described the tie-up as a blend of Prudential’s insurance know-how and the cloud firm’s AI strengths, delivering accuracy above 95% with low error rates.
Manulife has also been active on the technology front. It signed a memorandum of understanding with Ant Health to explore health management services, cross-boundary healthcare support, digital tools and insurance technology, including help with claims and payments for customers moving between Hong Kong and the mainland.
The agreement aims to smooth out the fragmented experience many policyholders face when arranging treatment across the border. Earlier in the year Manulife also struck a strategic partnership with Alibaba Cloud focused on building AI applications for customer experience, fraud detection and operations, with plans for a joint AI hub in Hong Kong.
BOC Life joined the wave by teaming up with Deloitte, rounding out a series of cross-sector moves.
These alliances come as Beijing has stepped up enforcement of existing rules that subject certain returns from offshore insurance policies to personal income tax at 20%. The change has prompted mainland clients to reassess Hong Kong products and created short-term uncertainty for insurers that rely heavily on that market.
Industry figures say the partnerships are less about reacting to any single rule change and more about long-term positioning. By linking up with technology and healthcare specialists, the insurers hope to speed up processes, offer better service and protect margins even if sales patterns shift.
Whether these deals deliver lasting advantages will depend on how smoothly the new systems integrate and how demand from mainland customers evolves in the months ahead, but the direction is clear: Hong Kong’s insurance sector is leaning harder on technology partners to adapt to a more complex regulatory environment.

.jpg)
.jpg)