India Plans Tough New Limits on Policy Commissions
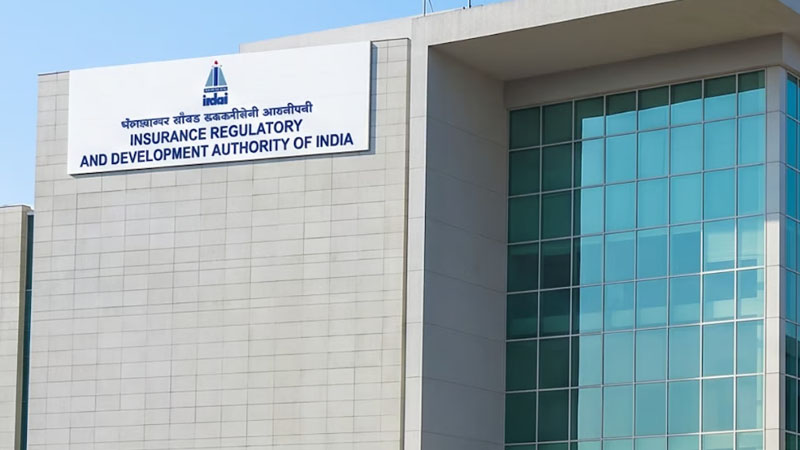
Int'l Insurance Desk: India’s insurance regulator has floated a sweeping set of proposals that would sharply limit the commissions paid to banks, brokers and agents for selling policies, a move intended to bring down costs for customers while putting pressure on the distribution networks that have driven much of the sector’s growth.
The Insurance Regulatory and Development Authority of India released a discussion paper late on Wednesday outlining the changes. The plans reverse a 2023 decision that had removed product-specific commission ceilings and form part of a broader push to reform the industry after the government allowed 100% foreign ownership earlier this year. Officials say the goal is to make insurance more affordable and reduce mis-selling by tying payouts more closely to the complexity of each product.
Under the draft rules, banks and brokers that sell policies from multiple insurers would face tighter limits than agents tied to a single company. In life insurance, first-year commissions for banks and brokers could fall to between 5% and 20% of the premium, down from rates that often exceed 40% today. The regulator also wants large upfront payments spread across the full term of a policy rather than concentrated in the first year. Health insurance commissions would be capped at 15% in the first year and 5% on renewals, compared with more than 30% in many cases now. Compulsory third-party motor cover on new vehicles would carry no commission at all.
The proposals go further. Insurers would face lower overall expense-of-management limits over the next few years, and banks and non-bank lenders would be barred from forcing customers to buy insurance when taking out loans. Stakeholders have until October 25 to submit comments before the rules are finalised.
Markets reacted quickly. Shares of PB Fintech, the parent of Policybazaar, plunged more than a third on Thursday as investors priced in a hit to its non-life business. The company’s co-founder told analysts the changes could cut general-insurance revenue to between one-third and 40% of current levels, prompting plans to slow hiring and review marketing and support costs. Other banks and insurers with large distribution income also saw declines, wiping billions of dollars from the sector’s market value in a single session.
The regulator argues the overhaul will ultimately expand coverage by making products cheaper and more transparent. Distributors, however, warn that lower incentives could slow new business and force a rethink of how insurance is sold across India.