USA vs Russia: Who is winning the Insurance Cold War?
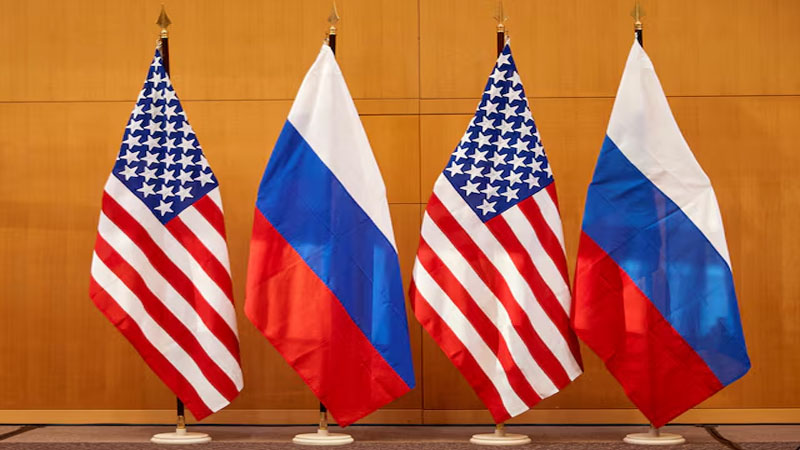
Global Insurance Desk: The United States and Russia offer insurers two starkly different propositions. One is the world’s dominant, highly mature market with enormous absolute scale, deep product sophistication and high household wealth. The other is a much smaller, faster-growing market still building penetration from a low base, shaped by compulsory lines, domestic capital and ongoing economic and regulatory adjustments.
The US insurance market remains by far the largest in the world. According to Swiss Re Institute data, US premiums reached approximately $3.5 trillion in 2024, accounting for nearly 45% of global volume. Property and casualty alone wrote nearly $976 billion in net premiums in 2025, while life, annuity and health lines add further massive scale. Russia’s market is orders of magnitude smaller. Central Bank and rating-agency figures put total premiums at roughly 3.9–4.0 trillion rubles in 2025 (around $40–45 billion at prevailing exchange rates), with forecasts for about 4.47 trillion rubles in 2026. That leaves the US market roughly 70–80 times larger in absolute terms.
Growth trajectories diverge sharply. Swiss Re projects global real premium growth of only 1.3% in 2026 and 1.6% in 2027 after stronger recent years. In that context the US is expected to expand more modestly consistent with a mature market while Russian forecasts from ACRA point to roughly 15% nominal growth in 2026, led by non-credit life insurance (around 16%) and motor lines (15–16%). Even with that differential, the absolute gap remains vast. Premiums per capita and penetration illustrate the disparity: US insurance density runs into thousands of dollars per person with penetration well into double digits of GDP in many segments, whereas Russian penetration stands near 1.9–2% of GDP and average household spending on insurance remains modest.
John Zhu’s observation on India and China applies equally here: impressive percentage growth in a smaller market must be weighed against starting points, exchange-rate effects, product mix and regulation. Russia still has substantial room to raise formal coverage. Compulsory motor third-party liability (OSAGO), voluntary comprehensive motor (KASKO), voluntary medical insurance and accumulating life products continue to expand. Digital distribution and bank-linked channels are improving access. Yet many households face limited disposable income for long-term regular-premium products, and distribution outside major cities remains uneven.
The US advantages rest on higher household wealth, established demand for retirement, long-term care, liability, cyber, specialty and sophisticated commercial covers, plus deep capital markets and a highly developed broker and agency system. Profitability in either market ultimately depends on underwriting discipline, pricing, distribution economics, claims experience, capital management and investment performance rather than demographics or size alone.
Both markets face margin pressures, though of different kinds. In the US, the multi-year hard market has softened; commercial property rates have fallen sharply in 2026, personal auto is more competitive after years of rate increases, and catastrophe losses remain elevated on a multi-year basis. Reserve releases and investment income have supported strong results, but the combined ratio is expected to normalize upward. In Russia, regulated tariffs in compulsory lines, inflation in claims (especially motor), and the need to manage investment returns amid high interest rates create their own challenges. Concentration is high the top 20 insurers write over 90% of premiums and foreign participation remains limited.
Globally the insurance industry is expected to slow, with Swiss Re projecting real premium growth of 1.3% in 2026 and 1.6% in 2027. Against that backdrop the US retains the vastly larger absolute pool of consumer and commercial demand, sophisticated risk transfer capacity and higher spending power. Russia offers faster percentage growth and rising penetration from a low base, but remains constrained by scale, economic volatility and a more limited product set.
Insurers must weigh the chance to participate in a still-expanding Russian market against the far higher absolute volumes, product depth and established demand already present in the United States. Neither path automatically delivers superior profits. Distribution costs, regulation, pricing accuracy, claims experience and capital efficiency will decide returns over the long term.
.jpg)

.jpg)