Airline Insurers Prepare for Busy Fourth Quarter Renewals
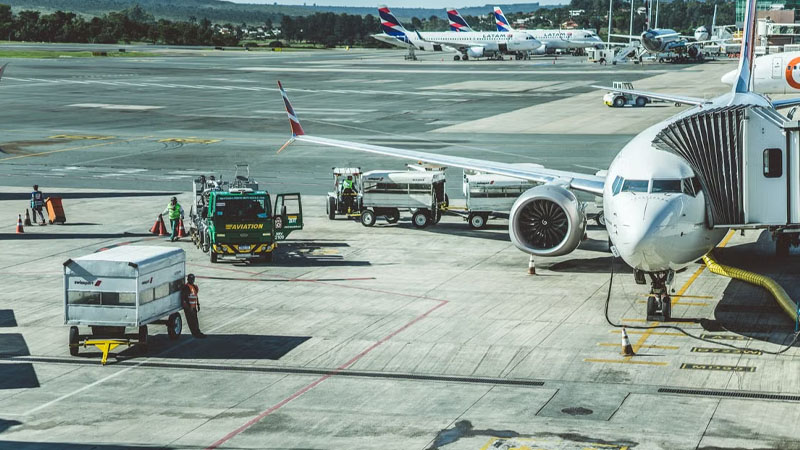
Insurance News Desk: Airline insurers are heading into the final quarter of 2026 with a generally stable market but a clear sense of caution. The period matters because it typically accounts for around 65 percent of the year’s lead hull and liability premiums. Capacity remains plentiful, which continues to support competitive pricing for airlines that can show strong loss records and solid risk management. War insurance has been softening under the weight of that capacity, while hull and liability underwriters are mostly looking for rate increases, though the picture still varies by region.
Liability claims have stayed limited through most of 2026 even as some sizable hull losses emerged. An early September runway overrun in Miami involving a cargo jet is expected to produce both hull and liability claims and could become a turning point as renewal talks gather pace. Underwriters are watching accumulation risk more closely, the danger that one event hits multiple policies at once. That focus has sharpened since the 2022 episode in which Russia retained more than 400 leased aircraft and triggered years of litigation. Insurers are also mapping fleet concentrations at individual airports in higher risk zones and considering newer threats such as potential mass drone attacks on grounded aircraft.
Geopolitical tension in the Middle East has already weighed on passenger demand and jet fuel prices. International Air Transport Association figures showed global passenger traffic up only 0.2 percent in July 2026 compared with the same month a year earlier. Outside the Middle East the rise was 1.2 percent. Insurers have so far managed the regional tensions without issuing cancellation notices, yet any unexpected drop in passenger volumes can still affect renewal pricing because those negotiations rest on forecasts of fleet values and traffic levels.
For now the surplus of capacity is expected to keep many renewals competitive, especially for well managed carriers. Industry observers note, however, that the balance can shift quickly. Another major loss or a further geopolitical shock could tighten available capacity and push premiums higher across the sector. The analysis draws on recent market commentary including outlooks from brokers such as WTW.
.jpg)