Japan vs South Korea: Who is the Asian Insurance Juggernaut?
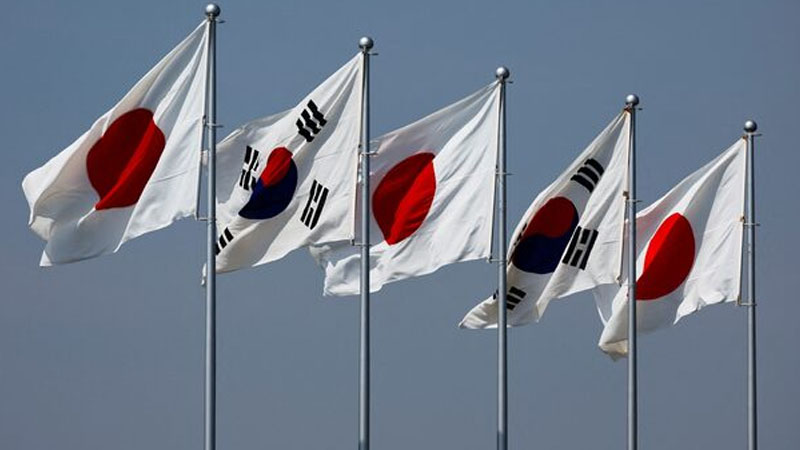
Int’l Insurance Desk: Japan and South Korea present insurers with two mature yet contrasting opportunities in advanced Asia. One remains larger in absolute premium volume and ranks among the world’s top five markets, while the other delivers higher insurance density, stronger penetration relative to GDP, and a more robust medium term growth outlook.
Japan generated about $327 billion in total insurance premiums in 2025 according to Swiss Re Institute figures, placing it fifth globally with roughly 3.9% of world volume. Life insurance continues to dominate, supported by savings and annuity products in a higher interest rate environment. Non-life premiums, including a large motor segment, form a smaller but significant share. South Korea ranked ninth with approximately $186 billion in premiums the same year (Allianz estimates put the figure near $176 billion). That leaves Japan’s market nearly twice the size of South Korea’s in absolute terms.
Growth trajectories diverge. Swiss Re projects very modest real premium expansion for Japan in 2026, around 0.3% for both life and non-life, before stabilising near long term averages of 0.6 to 0.9%. An ageing and shrinking population constrains traditional protection demand, though savings products and selective non-life lines such as liability and cyber retain some momentum. South Korea shows stronger prospective growth. Allianz forecasts property and casualty premiums rising at an average 4.9% annually and life at 4.4% through 2036, potentially lifting the overall market toward $290 billion. Local projections from the Korea Insurance Research Institute point to more moderate near term expansion of about 2.3% in 2026 after stronger recent years.
Penetration and density highlight South Korea’s relative strength. Japanese insurance premiums equated to roughly 7.4% of GDP in 2025, with spending near $2,450 per person. South Korea’s penetration stood at 9.4 to 9.8% of GDP, one of the highest rates in Asia, with average spending around $3,400 per capita. Both markets are sophisticated by global standards, yet South Korea’s higher ratios reflect deeper household engagement with both life and non-life covers.
Japan’s advantages rest on absolute scale, a well-established regulatory framework, and deep pools of existing demand for retirement, savings, and catastrophe related products. The market is adapting to sustained inflation, higher rates, and an economic value based solvency regime. Challenges include demographic headwinds, moderating property growth after recent catastrophe driven rate adjustments, and soft real growth in motor. Distribution remains mature but faces pressure to innovate around digital channels and new risks such as cyber.
South Korea benefits from higher current penetration, solid demographic support for health and pension products, and room for continued expansion in long term and liability lines. Compulsory and voluntary motor covers remain important, while general agencies have expanded rapidly. Margin pressures exist through intense competition, claims inflation in motor, and the transition effects of IFRS 17 on contractual service margins. Insurers must also navigate household debt levels and real estate dynamics.
Both markets face the broader industry slowdown projected by Swiss Re, with global real premium growth expected at 1.3% in 2026 and 1.6% in 2027. Against that backdrop Japan retains the larger absolute pool of demand and a highly developed product set, while South Korea offers higher density, stronger penetration, and superior percentage growth prospects over the coming decade.
Insurers must weigh Japan’s scale and established sophistication against South Korea’s denser coverage and faster expansion trajectory. Neither path automatically delivers superior profits. Underwriting discipline, pricing accuracy, distribution economics, claims experience, and capital management will ultimately decide long term returns.