Regulatory Spotlight Falls on Motor Cover and CEO Pay in Indian Insurance Sector
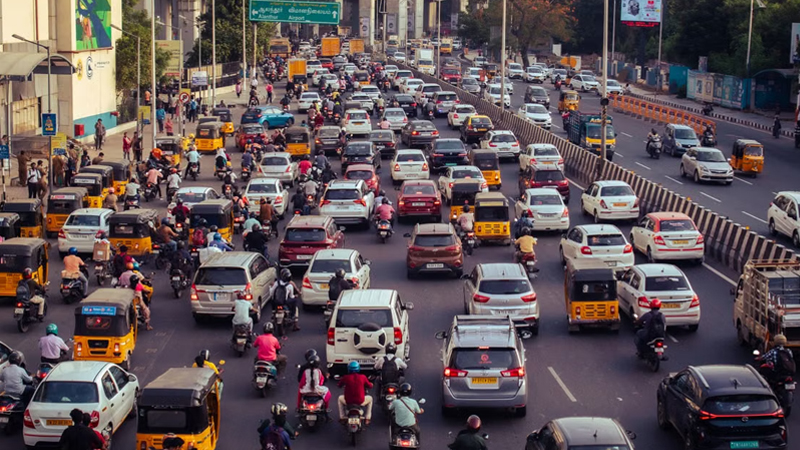
Int’l Desk: Regulatory developments in India’s insurance sector have drawn fresh attention this month, particularly around motor third-party cover and executive compensation rules. The Supreme Court recently directed the insurance regulator to examine longer mandatory tenures for motor third-party policies along with steps to improve overall coverage levels. The move prompted shares of general insurers to rise as markets weighed the possible effects on premium volumes and claims patterns.
Industry observers note that extending the duration of compulsory third-party motor insurance could lift upfront costs for vehicle owners while also increasing pressure on commissions paid to intermediaries. Critics of the proposal argue it may do little to solve the persistent problem of uninsured commercial vehicles, yet the court’s intervention has still focused minds on how the existing system might be strengthened. Shares of several general insurance companies advanced after the directions became public, reflecting expectations of higher premium collections even if the practical impact on road safety remains uncertain.
At the same time, the Insurance Regulatory and Development Authority of India has tightened its approach to executive pay. Recent disclosures showed that some life insurance chief executives received substantial remuneration packages for the latest financial year, with Bajaj Life’s chief executive standing out at more than three times the level of the next highest-paid peer. The regulator’s closer scrutiny of compensation structures has coincided with these reported increases, raising questions about governance standards and the alignment of pay with long-term performance.
Taken together, the Supreme Court’s motor third-party directions and the regulator’s focus on executive remuneration have placed two distinct but concurrent issues under the spotlight. One concerns the affordability and reach of compulsory motor cover; the other examines how senior leadership packages are set and disclosed. Both developments, reported in Business Standard earlier this month, underscore the regulator’s and the court’s willingness to intervene in areas that directly affect policyholders, intermediaries and the broader insurance market.
.jpg)