848 Crore Taka Vanished from Prime Islami Life’s Fund Through Misappropriation and Manipulation (Part 2)
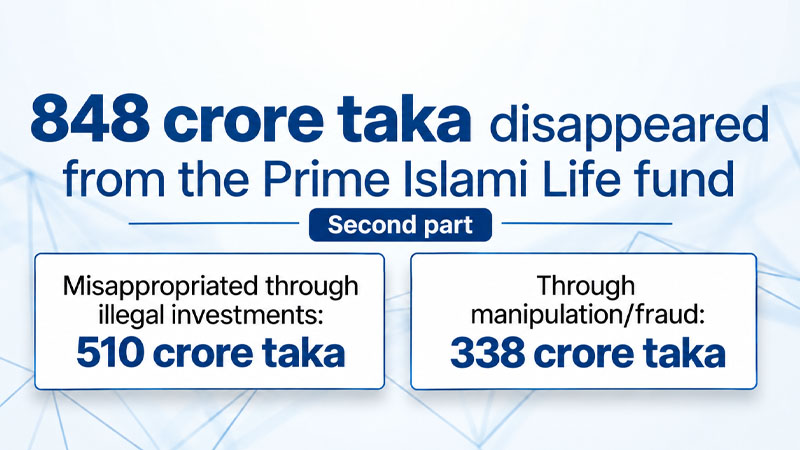
Abdur Rahman Abir: Through misappropriation and manipulation, 848 crore taka has vanished from the fund of Prime Islami Life. The diversion of money from the company’s fund began in 2011. Although these incidents of misappropriation have come to light at various times, no effective steps have been taken to recover the misappropriated money. Even the regulatory body has taken no action. As a result, the company has lost the financial capacity to pay policyholders’ dues. This picture of Prime Islami Life’s financial condition has emerged from an investigation by Insurance News BD.
According to the investigation, 510 crore 6 lakh taka was directly misappropriated from Prime Islami Life’s fund by showing illegal investments; 184 crore taka was removed from the fund through accounting manipulation; and 154 crore 67 lakh taka was lost from the fund due to overvaluation of land.
The investigation compared the company’s current assets with the misappropriated amounts and the liabilities owed to policyholders. Financial reports from 2015 to 2025, special audit reports, and related documents were examined and reviewed.
The review shows that Prime Islami Life has total liabilities of 1,455 crore 79 lakh taka. Of this, policyholders’ liabilities amount to 1,346 crore 91 lakh taka, and other liabilities total 108 crore 88 lakh taka. Assets shown for meeting these liabilities are 889 crore 17 lakh taka. If the misappropriated 510 crore 6 lakh taka is deducted from the assets, the remaining assets stand at 379 crore 11 lakh taka. This results in a shortfall of 1,076 crore 68 lakh taka.
However, this shortfall calculation does not end here. Of the 889 crore 17 lakh taka in assets, 278 crore 63 lakh taka is shown under land and buildings. This figure is also incorrect. Land values have been inflated by 154 crore 67 lakh taka. Additionally, 184 crore taka has been embezzled through manipulation.
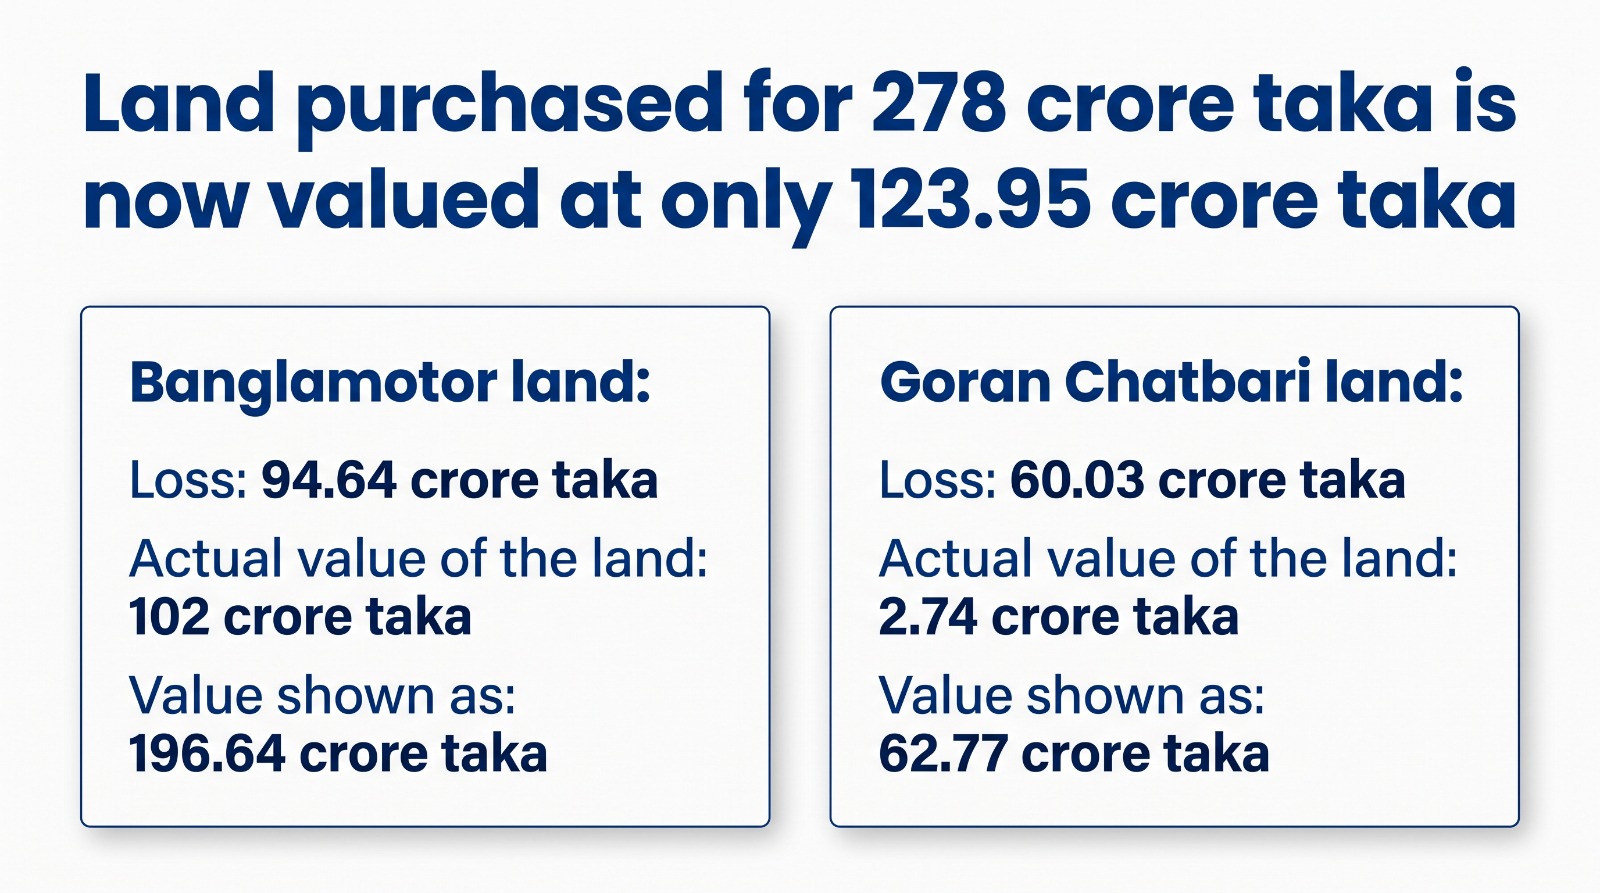
If the manipulation and excess land valuation are taken into account, the amount of assets will decrease further, and the shortfall in meeting liabilities will increase even more.
The investigation found that the areas of direct misappropriation include:
• Investment in the subsidiary Prime Islami Life Securities: 141 crore 82 lakh 86 thousand 149 taka
• Illegal loans given in the name of investment in PFI Securities: 188 crore 11 lakh 13 thousand 662 taka
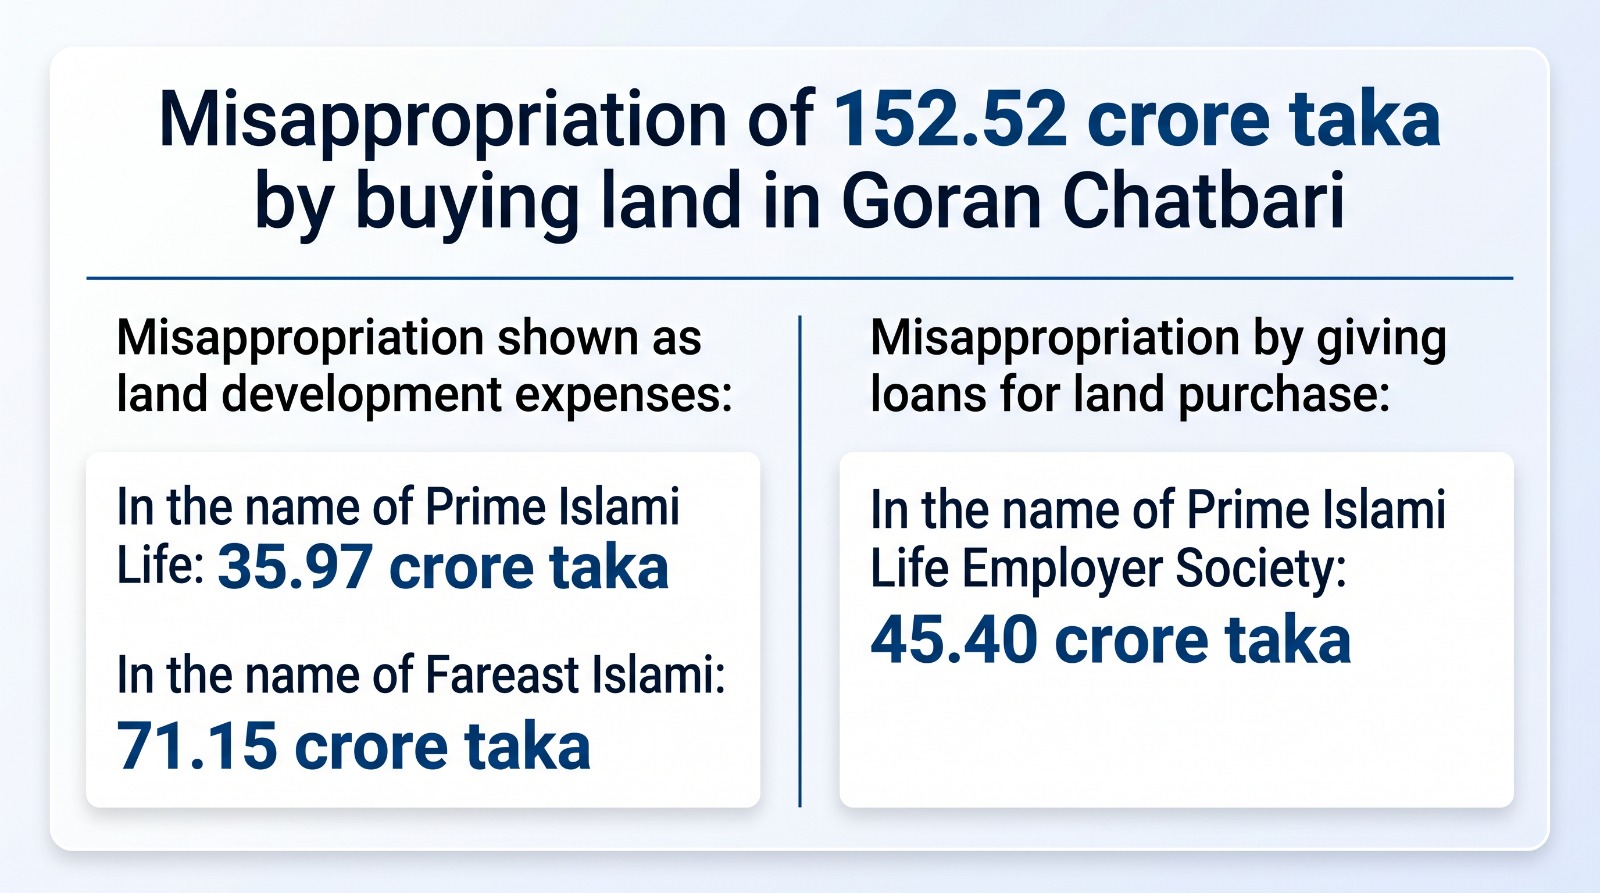
• Misappropriation in the name of land purchase and development: 152 crore 52 lakh taka
• Misappropriation in the name of investment in other organisations: 23 crore 5 lakh 58 thousand taka
• Amount taken by former Chairman M. A. Khalek: 4 crore 55 lakh 55 thousand taka
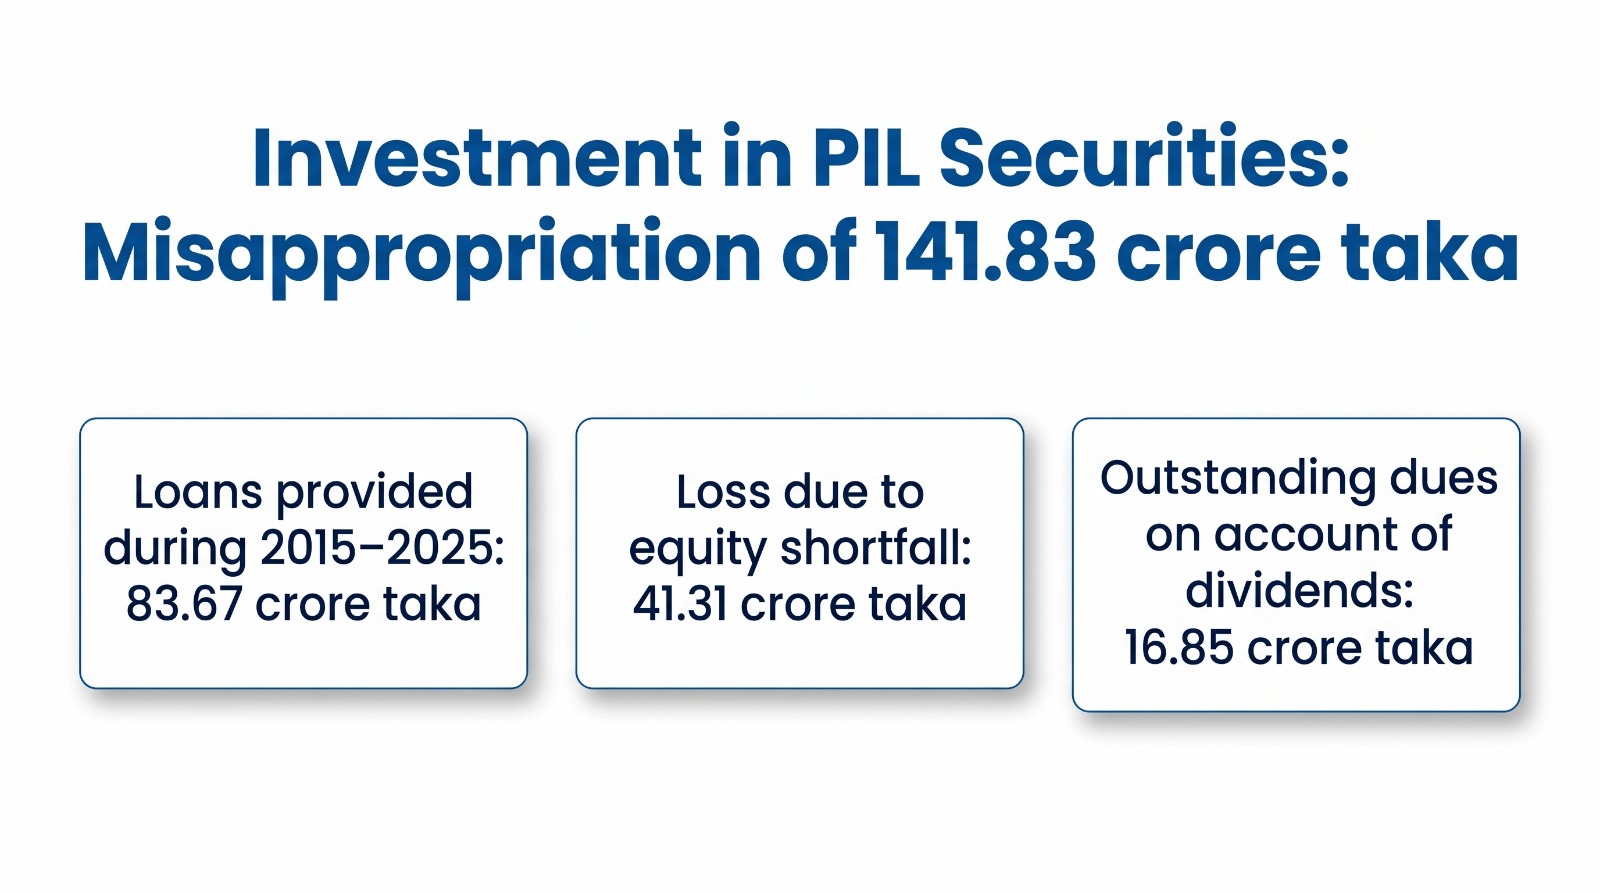
The investigation also found that through accounting manipulation, the company’s life fund was inflated by 184 crore taka (i.e., this money was removed from the fund). This manipulation was done through false information and padding in items such as outstanding premiums, Tabarru fund, and collection balance. In addition, money was misappropriated by showing land purchases at inflated prices in Goran Chatbari and Banglamotor.
Paper Life Fund of 184 Crore Taka Created Through Accounting Manipulation
According to accounting principles, money that has not been collected or has no chance of being collected cannot be shown as part of the life fund. Yet, in violation of these rules, Prime Islami Life added 183 crore 53 lakh taka of uncollected and non-recoverable amounts to the life fund, thereby inflating it. These amounts include losses in the share market as well as outstanding premiums. The life fund was also inflated by showing income under the unusual heading of “collection balance.” Prime Islami Life has been inflating its life fund through such manipulation year after year.
The investigative report of Insurance News BD is based on a review of financial reports covering the 11 years from 2015 to 2025, identifying the areas where money was embezzled from the fund through manipulation.
Outstanding Premiums of 54 Crore 86 Lakh Taka: Questions Over Collection
According to financial reports, up to 2024 Prime Islami Life has shown outstanding premiums of 54 crore 86 lakh taka, which is 22.39% of total premiums.
A review of the outstanding premium figures shows that the amount reported by Prime Islami Life is highly abnormal. There is also no information on whether these outstanding premiums have actually been collected.
In 2024, the company earned 245 crore 8 lakh taka in renewal premiums over 11 months — an average of 17 crore 29 lakh taka per month. Yet in the single month of December it claimed 54 crore 86 lakh taka in renewal premiums.
There is doubt as to whether this amount was actually earned. Nevertheless, the entire outstanding premium amount was added to the life fund, inflating it by 54 crore 86 lakh taka of questionable outstanding premiums.
36 Crore 99 Lakh Taka Illegally Deducted from Policyholders’ Claims to Create Tabarru Fund
According to financial reports, in 2024 Prime Islami Life deducted 18 crore 49 lakh 40 thousand 874 taka from insurance claim payments to create a Tabarru fund. Under the rules, a Tabarru fund is formed by deducting a portion from premiums.
All amounts paid as insurance claims are deducted as expenses in the life revenue account when calculating the life fund. However, Prime Islami Life did not deduct the Tabarru fund amount retained from claims as an expense in the life revenue account.
As a result, because the Tabarru fund was not created from premiums, premium income increased. At the same time, because an equivalent amount of claims was not paid, claim payments decreased. This caused the life fund to increase by twice the amount of the Tabarru fund. Through this accounting manipulation, the life fund was inflated by 36 crore 98 lakh 81 thousand 748 taka.
“Collection Balance” of 33 Crore 11 Lakh Taka Also Added to the Life Fund
There is no heading called “collection balance” in the financial reports of life insurance companies. Yet Prime Islami Life created such a heading in its financial reports and has been showing crores of taka under it year after year, without any description of what the money represents.
A special audit by SF Ahmed & Co. noted that the amounts shown under collection balance were first-year premium income. Under the law, first-year premiums cannot be kept outstanding.
According to the special audit, in 2017 collection balance was shown as 40 crore 24 lakh taka, all of which was first-year premium income. These first-year premiums were collected by Prime Islami Life until March of the following year (2018). Under the law, first-year premium collection must be completed by 31 December.
The audit report further stated that the firm could not verify the amount of next-year first-year premiums included in collection balance in other years because Prime Islami Life did not provide relevant documents.
A review of financial reports shows that in 2025 collection balance was shown as 33 crore 11 lakh taka (25.62% of that year’s first-year premium income). In 2014 it was shown as 37 crore 30 lakh taka (67.74% of first-year premium income).
From 2014 to 2025, collection balance was shown as ranging from 25.62% to 70.38% of first-year premium income in different years.
Accountants say that showing the next year’s premium income in the previous year is accounting manipulation and has no legal validity. Inflating both premium income and the life fund through this method is illegal. Yet the entire collection balance amount (33 crore 11 lakh taka) was added to the life fund.
Share Market Loss of 18 Crore 65 Lakh Taka Also Kept in the Life Fund
According to the 2025 financial report, Prime Islami Life invested 35 crore 81 lakh 65 thousand 919 taka in share trading. The current market value is 17 crore 16 lakh 54 thousand 482 taka. Thus the company incurred an unrealised loss of 18 crore 65 lakh 11 thousand 437 taka in the share market. Instead of deducting this amount from the life fund, Prime Islami Life kept it in the fund, thereby inflating it.
VAT Evasion of 7 Crore 55 Lakh Taka; Outstanding 10 Crore 1 Lakh Taka
Prime Islami Life collected 11 crore 9 lakh 59 thousand 832 taka as VAT from various organisations but deposited only 5 crore 4 lakh 16 thousand 636 taka into the government treasury. The remaining 6 crore 5 lakh 43 thousand 196 taka was not deposited.
A review of financial reports shows that in 2024, when filing returns, the company showed agent commission payments of 6 crore 97 lakh 1 thousand 300 taka, whereas it actually paid 36 crore 85 lakh 39 thousand 125 taka. Thus commission payments were understated by 29 crore 88 lakh 37 thousand 825 taka. Tax at source on this amount at 5% comes to 1 crore 49 lakh 41 thousand 891 taka, which was also not paid to the government.
In 2015, outstanding tax and VAT stood at 1 crore 14 lakh taka. This has increased every year and stood at 10 crore 1 lakh taka in 2025. Prime Islami Life deducted this VAT and tax but did not deposit it into the government treasury.
Overall, the company has evaded 7 crore 55 lakh taka in VAT and has not paid a total of 10 crore 1 lakh taka in VAT and tax. All of this money has been retained in the fund, inflating the life fund.
Uncollected MTDR of 5 Crore 72 Lakh Taka Also Added to the Life Fund
A review of financial reports shows that Prime Islami Life invested 5 crore 72 lakh 26 thousand 953 taka in seven MTDRs with Global Islami Bank and showed interest income of 15 lakh 36 thousand 953 taka.
Of these seven MTDRs, four are from 2021 and three from 2024. The bank has been loss-making since 2023. As a result, Prime Islami Life has been unable to recover any money from the bank, and recovery is uncertain.
Yet the company has been automatically renewing the MTDRs every year, adding the amounts as income to the life fund, and also showing them as investments to inflate assets. Questions have also been raised about why new investments were made in a loss-making bank.
Uncollected Policy Loans and Profit of 15 Crore 81 Lakh Taka
A review of financial reports shows that from 2015 to 2025 (10 years), the company gave 41 crore 64 lakh taka in loans to policyholders. Of this, only 29 crore 47 lakh taka has been recovered. The remaining 12 crore 17 lakh taka (29.23% of total loans) remains uncollected. Life insurance companies can give policy loans for only one year.
Despite non-recovery of the loans, the company has been claiming profit on them in its financial reports, and this profit has been increasing every year. As of 31 December 2025, profit from policy loans was shown as 3 crore 64 lakh taka. There are questions about whether this amount will be recovered. This amount has also been added to the life fund. Altogether, 15 crore 81 lakh taka has been added to the life fund under this head.
Advance Salary Shown as Paid, Inflating Life Fund by 16 Lakh Taka
According to the special audit report of SF Ahmed & Co., from 2021 to 2024, 16 lakh 5 thousand 388 taka was shown as advance to seven officers. This advance salary has been shown as paid year after year. These officers are no longer employed by the company, and there is no explanation in the financial reports of how this money is recoverable from former employees. Yet this amount has also been added to the life fund.
Uncollected Dues of 67 Lakh Taka from Six Organisations
According to the 2025 financial report, Prime Islami Life is owed:
• 20,486 taka from Prime Islami Securities
• 5,716 taka from Fareast Islami Securities
• 24 lakh 68 thousand 587 taka as BGTB premium
• 6 lakh taka from Global Islami Bank
• 35 lakh 56 thousand 109 taka under other (untitled) heads
Total dues: 66 lakh 50 thousand 968 taka.
There is no certainty that these amounts will be recovered. Under accounting principles, such outstanding amounts cannot be shown as assets. Yet Prime Islami Life has shown them as assets and inflated the life fund.
211 Crore Taka Spent in Six Heads Excluding Salaries & Allowances: 6 Crore 43 Lakh on Tea Alone
Excluding salaries and allowances, Prime Islami Life has spent 211 crore 41 lakh taka in eight heads over the past 11 years — an average of 19 crore 22 lakh taka per year. Of this, 6 crore 43 lakh taka was spent on tea alone.
The company has 1,025 officers and staff, 118 offices across the country, and 61 vehicles.
• Travelling and conveyance: 114 crore 88 lakh taka (average 10 crore 44 lakh per year, or 87 lakh per month)
• Development meetings and conferences: 17 crore 57 lakh taka (average 1 crore 59 lakh per year)
• Vehicle fuel and repairs: 44 crore 44 lakh taka (average 4 crore 4 lakh per year, or 33.36 lakh per month)
• Electricity and telephone: 23 crore 4 lakh taka (average 2 crore 9 lakh per year, or 17.41 lakh per month)
• Office hospitality and tea: 6 crore 43 lakh taka (58.48 lakh per month)
• Other general office expenses: 5 crore 4 lakh taka (46 lakh per year, or 4 lakh per month)
Padding of Accounts: 14 Crore 68 Lakh Taka of Expenses Hidden
Under the law, management expenses of a life insurance company are calculated after excluding claim payments and capital expenditure; all other expenses are included. Yet Prime Islami Life excluded nine heads of expenditure when calculating management expenses. These include rates and taxes, interest expenses, depreciation of fixed assets, UMP costs, National Insurance Day expenses, bad debts, and losses on share sales.
Over the past 11 years (2015–2025), expenditure under these nine heads totalled 39 crore 95 lakh taka. Prime Islami Life did not include this amount in management expenses.
In its financial reports, the company showed management expenses of 1,413 crore 85 lakh taka over 10 years. If the 39 crore 95 lakh taka is included, actual management expenses become 1,453 crore 80 lakh taka.
The approved management expense limit was 1,439 crore 20 lakh taka. Thus there was an excess expenditure of 14 crore 68 lakh taka. Yet the company reported that management expenses were 25 crore 27 lakh taka lower than the limit.
98 Lakh Taka Paid to 72 Unlicensed Agents
According to the special audit report of SF Ahmed & Co., from 2021 to 2024 commission of 98 lakh 14 thousand 234 taka was paid to 72 agents without licences. Paying commission to unlicensed agents is illegal.
99 Lakh Taka Misappropriated in the Name of Dividend
The investigation found that the 2021 valuation report stated that Prime Islami Life had a deficit of 676 crore 99 lakh 84 thousand 990 taka. Despite this deficit, directors and shareholders took dividends from 2023 to 2025.
A review of financial reports shows that directors and shareholders took:
• 2% (61 lakh 4 thousand 46 taka) in 2023
• 1% (30 lakh 52 thousand 23 taka) in 2024
• 0.25% (7 lakh 63 thousand 6 taka) in 2025
Total dividends taken over three years: 99 lakh 19 thousand 75 taka. The law requires this money to be returned.
Full Premium Amounts Are Not Deposited in Banks; Expenses Are Made in Cash
The entire premium amount must be deposited in the bank, and there is no provision for cash expenses. Yet Prime Islami Life has been deducting expense amounts from premiums and depositing only the remainder in the bank. It has also paid agents’ expenses in cash, including commissions to unlicensed agents.
A review of financial reports shows that the City Service Centre of Prime Islami Life collected 3 crore 87 thousand 145 taka in premiums from 2022 to 2024. Of this, 88 lakh 12 thousand 266 taka was spent, and only the remainder was deposited in the bank.
The City Service Centre also made cash payments from premiums for commission, salaries and allowances, SB, maturity claims, travelling expenses, mobile bills, incentives, etc.:
• 2022: 34 lakh 31 thousand 60 taka
• 2023: 50 lakh 19 thousand 898 taka
• 2024: 1 crore 63 lakh 39 thousand 948 taka
What Prime Islami Life Says
Regarding the allegations of hiding expenses and inflating the life fund through accounting manipulation, Chief Executive Officer Md. Samsul Alam of Prime Islami Life told Insurance News BD:
“Almost all of the allegations that have come up here are from a long time ago. Moreover, in life insurance, premium income is higher at the end of the year, which is why outstanding amounts appear high. Although expenses in various heads are higher, our total management expenses have been lower.”
.jpg)