COSCO SHIPPING Captive Posts Marginal Underwriting Losses
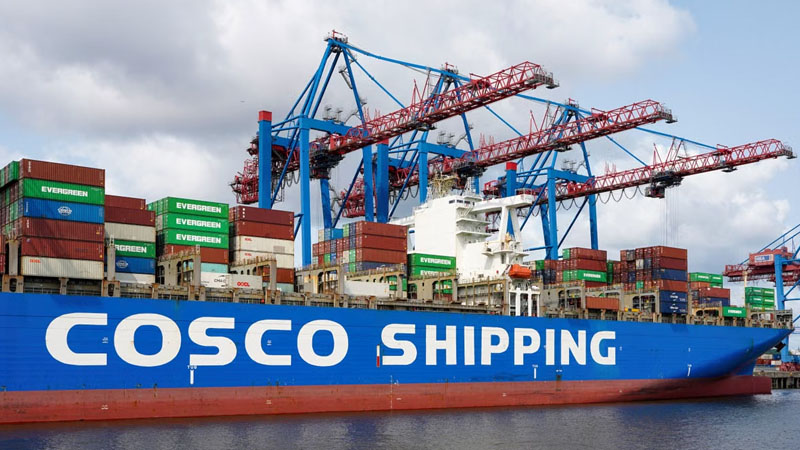
Global Insurance Desk: COSCO SHIPPING Captive Insurance posted marginal underwriting losses in the latest period even as the company continued its unbroken run of positive annual earnings that began in 2017. The small net losses stemmed mainly from the captive’s limited net earned premium base, which partially offset otherwise supportive underwriting factors such as steady marine hull premiums, favourable reinsurance commission income and low acquisition costs.
AM Best still views the overall picture as solid. The rating agency assigns the captive a stable medium-term outlook and highlights its very strong balance sheet strength, adequate operating performance, neutral business profile and appropriate enterprise risk management. Risk-adjusted capitalisation remains well above the threshold for the strongest assessment under Best’s Capital Adequacy Ratio, helped by low underwriting leverage, a conservative investment approach and a comprehensive reinsurance programme.
As a strategically important subsidiary of China COSCO SHIPPING Corporation Limited, the captive receives ongoing support in business development, risk management and capital. AM Best expects profitable group-related business and stable investment returns to keep driving capital growth through retained earnings. Between 2021 and 2025 the company delivered an average return on equity of 5.3%. Investment results stayed consistent, producing a net yield of 2.9% in 2025 when capital gains are included, thanks to a portfolio concentrated in fixed-income assets.
Most of the underwriting book centres on marine hull cover for the parent group and its affiliates, with additional exposure in liability, commercial property, cargo, motor, accident and health lines. Distribution flows through direct channels and internal brokers that give the captive closer visibility into group risks.
.jpg)